M&A in Australasia - 2026 Q3
(Originally published on October 1, 2026)
We have recently reallocated Timor-Leste to Southeast Asia rather than Australia. For Q3 2026, however, we have included it within both our Southeast Asia and Australasia regional reviews, with the change reflected retroactively in the regional analysis.
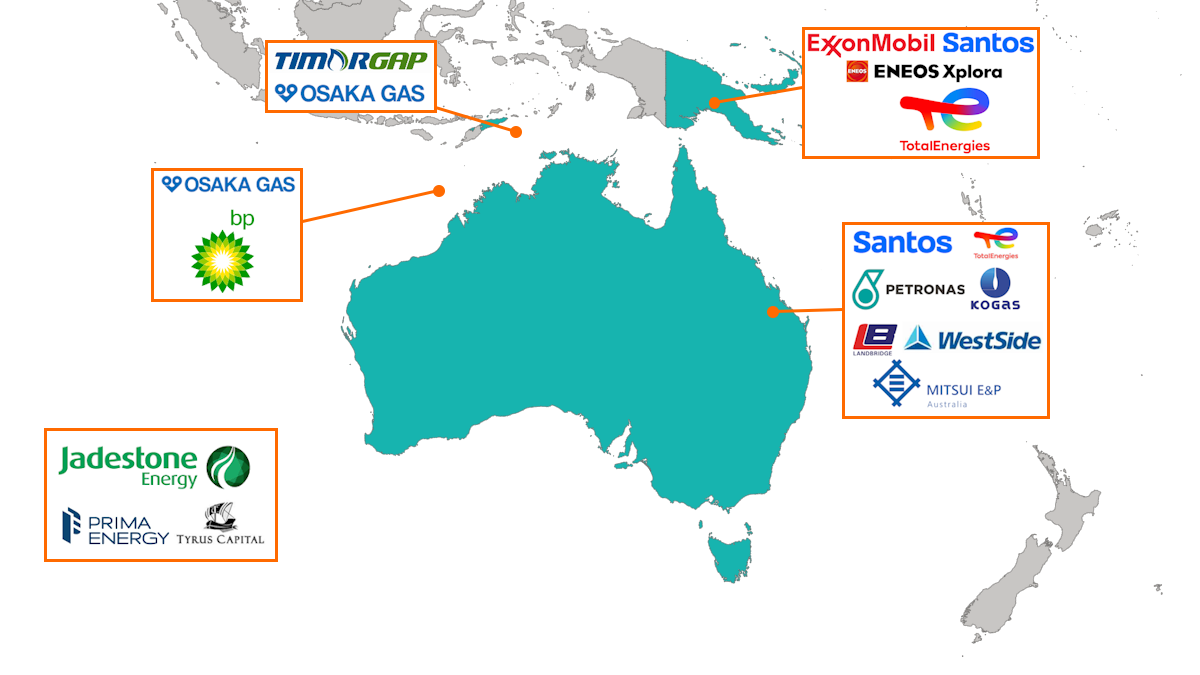
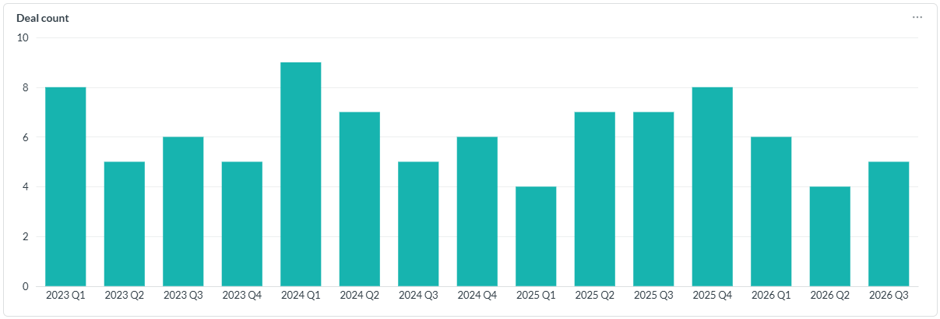
Q3 saw five deals announced across Australasia. These comprised two Australian asset transactions, one regional corporate shareholding transaction involving Jadestone Energy, one Timor-Leste project transaction, and one Papua New Guinea LNG farm-down.
Two of the five deals included disclosed transaction-value information. The GLNG partners agreed to acquire the Greater Meridian CSG Project for A$430 million, or approximately US$310 million. For Papua LNG, Santos disclosed that it will pay approximately US$189 million for its 3.3% tranche of the wider 9.1% farm-down by TotalEnergies, although the total consideration for the full transaction was not disclosed.
For our regional analysis, we use an illustrative pro-rata value of approximately US$521 million for the full Papua LNG farm-down. This gives a Q3 reference deal value of approximately US$831 million, although the Papua LNG figure should be treated as illustrative rather than a disclosed transaction value.
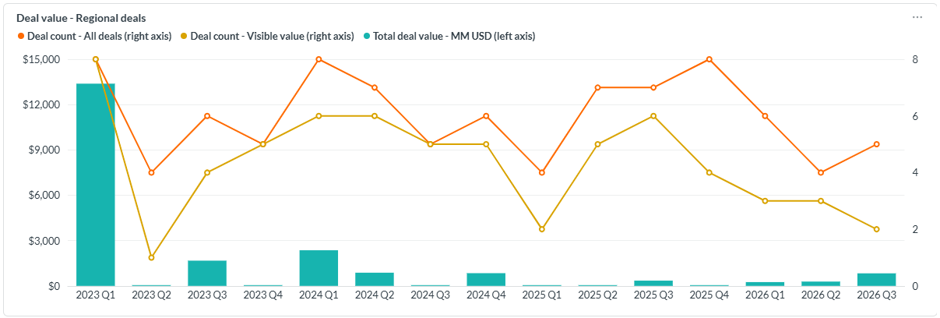
The rolling deal count for 2026 now stands at fifteen Australasia-related deals, with a reference deal value of approximately US$1.37 billion across eight deals with visible value. By comparison, at the end of Q3 2025 there had been eighteen Australasia-related transactions, with approximately US$386 million of visible deal value across twelve transactions.
New deals announced in Q3
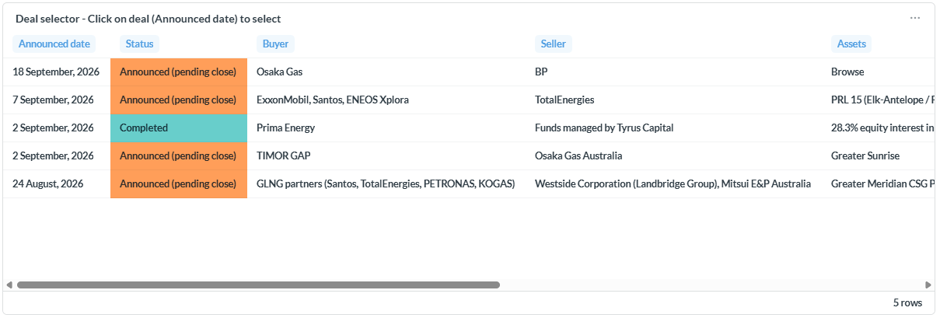
The five deals announced in Q3 were:
- In late-August, the GLNG partners — Santos, TotalEnergies, PETRONAS and KOGAS — agreed to acquire 100% of the producing Greater Meridian CSG Project in Queensland from Westside Corporation / Landbridge Group and Mitsui E&P Australia for A$430 million, or approximately US$310 million. The transaction has an economic effective date of 1 January 2026, is targeted to complete in late 2026, and Santos will become operator on completion. We looked at the deal in more detail here.
- In early-September, Prima Energy announced that it had acquired approximately 28.3% of Jadestone Energy from funds managed by Tyrus Capital. The private secondary share transaction gives Prima strategic exposure to Jadestone’s upstream portfolio across Australia, Malaysia, Indonesia and Vietnam. Prima also stated that it does not intend to make a full takeover offer. We looked at the deal in more detail here.
- Also in early-September, TIMOR GAP agreed to acquire Osaka Gas Australia’s 10% participating interest in Greater Sunrise. If completed, the transaction would increase TIMOR GAP’s interest from 56.56% to 66.56%, with Woodside retaining 33.44% and operatorship. The acquisition remains subject to governmental and regulatory approvals and other conditions. We looked at the deal in more detail here.
- In early-September, TotalEnergies agreed to sell a combined 9.1% post-State-back-in interest in PRL 15 / Papua LNG to existing partners ExxonMobil, Santos and ENEOS Xplora, reducing TotalEnergies’ interest to 20%. Santos disclosed consideration of approximately US$189 million for its 3.3% tranche, while the total consideration for the wider farm-down was not disclosed. Completion remains conditional on approvals and Papua LNG reaching FID, while operatorship is expected to transfer to ExxonMobil. We looked at the deal in more detail here.
- In mid-September, Osaka Gas agreed to acquire a 5% interest in the Browse project from BP. The consideration was not disclosed and completion remains subject to regulatory and Browse JV partner approvals. The transaction would sit alongside the other pending Browse ownership changes involving Woodside’s proposed acquisition of PetroChina’s 10.67% interest and GS Energy’s proposed acquisition of a further 5% from BP. Woodside has subsequently been reported as considering whether to exercise its pre-emption rights over the Osaka Gas transaction, although no formal exercise of those rights has been announced. We looked at the deal in more detail here.
The table below summarises the deals announced this quarter:
Deals that were cancelled in Q3
There were no Australasia-related deals cancelled during Q3.
Deals that closed in Q3
Q3 saw four transaction completions or implementation events across Australasia.
- On 1 July, Woodside Energy completed the transition to operatorship of the Gippsland Basin JV and Kipper Unit JV assets in Bass Strait from ExxonMobil. The transaction did not change participating interests but transferred operatorship of the long-established Bass Strait production system to Woodside.
- In early-July, Horizon Oil completed its off-market takeover of Cue Energy Resources, resulting in Horizon holding approximately 57.03% of Cue. The offer had become unconditional in June and closed on 19 June, with Horizon subsequently confirming completion of the transaction in early-July.
- In late-August, Comet Ridge completed its acquisition of Santos’ 42.86% operated interest in the Mahalo Gas Project, taking Comet Ridge to 100% ownership and operatorship. Final settlement included cash and shares, with a further A$30 million of contingent cash payments linked to future cumulative gas-sales milestones.
- In early-September, Prima Energy completed its acquisition of approximately 28.3% of Jadestone Energy from funds managed by Tyrus Capital. The transaction had effectively completed shortly before its public announcement, with Jadestone subsequently confirming Prima’s shareholding.
Previously announced deals still pending completion
At the end of Q3, seventeen Australasia-related transactions remain pending.
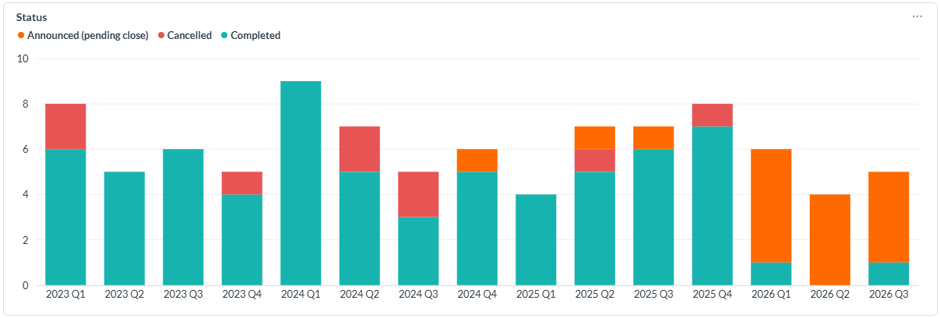
As with Southeast Asia, the position varies considerably. Some transactions are now close to completion, others form part of longer multi-stage ownership restructurings, while a small number have become increasingly uncertain.
- Pilot Energy / Triangle Energy — Cliff Head position increasingly uncertain.
The oldest outstanding deal dates back to 2022 and concerns Pilot Energy’s acquisition of Triangle Energy’s remaining interest in Cliff Head. The first-stage transfer of the onshore and Western Australian State-jurisdiction assets completed in June 2025, but the remaining offshore transfer was still pending when Pilot Energy and several subsidiaries entered voluntary administration in July 2026 after failing to secure funding or a strategic partner for the proposed Cliff Head carbon-storage development. There is therefore no credible current completion timetable for the remaining offshore transfer. - Woodside / Chevron — asset swap still targeted for H2 2026.
The December 2024 asset swap between Woodside and Chevron covers interests across North West Shelf LNG, NWS Oil, Angel CCS, Wheatstone and Julimar-Brunello. Woodside’s latest half-year reporting continued to assume completion during the second half of 2026, although transaction conditions remain outstanding. - Daly Waters / Tamboran — 2025 Beetaloo acreage sale and checkerboard remains in implementation.
The May 2025 Beetaloo transaction between Daly Waters Energy and Tamboran Resources has since become part of a wider acreage and development realignment. The parties executed the Stage 1 checkerboard sale and purchase deed in March 2026 and submitted retention-licence applications covering the relevant acreage. Completion remains subject to regulatory approvals and other conditions, with the related arrangements extending into late 2026 and 2027. - Koloma / Buru Energy — Canning Basin asset transfer still outstanding.
Koloma agreed in July 2025 to acquire selected Canning Basin acreage from Buru Energy for A$0.25 million. The separate acquisition of Buru’s 2H Resources business completed in August 2025, but the selected Canning Basin asset transfer remains outstanding. I have not seen a revised completion timetable. - MidOcean Energy / JERA — Gorgon transaction remains pending.
MidOcean Energy agreed in March to acquire JERA’s 0.417% interest in Gorgon LNG. The original transaction announcement also included JERA’s Ichthys interest, but that part of the deal changed during Q3 after INPEX exercised pre-emption rights. JERA confirmed in September that the Gorgon sale to MidOcean remains unchanged and is still pending completion. - INPEX / JERA — Ichthys transaction now clearly identified.
In September, INPEX confirmed that it had exercised its pre-emption rights over JERA’s 0.735% participating interest in Ichthys LNG, increasing INPEX’s interest from 67.82% to 68.555% if completed. The transaction remains subject to Australian regulatory approvals. No completion date has been disclosed. - ConocoPhillips / 3D Energi — buy-out right exercised, but the process remains disputed.
The VIC/P79 ownership dispute moved forward materially during Q3. Independent expert RISC Advisory determined the fair market value of 3D Energi’s 20% interest at US$19.8 million, and ConocoPhillips subsequently issued a notice purporting to exercise its JOA buy-out right.
The amount ultimately payable would be subject to a 5% JOA discount and further default-related deductions. 3D Energi continues to dispute the validity of the default and buy-out process, and the interest has not yet transferred. - INPEX / Daly Waters — Beetaloo farm-in remains pending.
INPEX’s March farm-in to Daly Waters Energy’s Beetaloo acreage remains part of the wider development and ownership realignment. Activity across the acreage has continued to advance, but I have not seen confirmation that the ownership transfer itself has completed. - Daly Waters / Tamboran — March 2026 farm-in also remains conditional.
The separate March farm-in by Daly Waters Energy to Tamboran’s Shenandoah Pilot Area and Beetaloo Central Development Area remains linked to the wider Tamboran / Daly Waters / INPEX restructuring. One major condition was cleared when Tamboran completed its acquisition of Falcon in May, but final implementation of the acreage arrangements remains outstanding. - Sunda Energy / Matahio — expected to complete shortly.
Sunda Energy’s acquisition of Matahio Energy NZ has advanced considerably. All relevant petroleum permits are now in good standing, including the new Puka/Oru mining permit, and Sunda raised additional equity funding principally to fund completion.
New Zealand Ministerial consent was expected in early October 2026, with the remaining net completion payment estimated at approximately US$3.6 million and completion expected shortly thereafter. - Woodside / PetroChina — Browse pre-emption transaction remains pending.
Woodside exercised its pre-emption right in June over PetroChina / CNPC’s proposed sale of a 10.67% Browse interest to INPEX. Woodside will acquire the interest on the matched terms, including US$225 million upfront and a possible further US$175 million contingent on Browse reaching FID by June 2032.
I have not seen a subsequent completion announcement or firm closing date. - Amplitude / O.G. Energy / Beach — Artisan transaction still awaiting completion.
Amplitude Energy and O.G. Energy agreed in May to acquire Beach Energy’s 60% operated interest in VIC/L35, including the Artisan gas discovery. Development activity has continued to progress, but the transfer remains pending regulatory and other approvals. No firm current completion date has been disclosed. - GS Energy / BP — first Browse 5% sale remains pending.
GS Energy’s acquisition of a 5% Browse interest from BP, announced in June, remains pending. The transaction would reduce BP’s interest from 44.33% to 39.33%. No transaction value or firm completion timetable has been disclosed. - GLNG partners / Greater Meridian — targeted for late 2026.
The newly announced Greater Meridian acquisition remains subject to regulatory and other approvals, with completion targeted for late 2026. As one of the new Q3 transactions, it is discussed in more detail above. - TIMOR GAP / Osaka Gas — Greater Sunrise awaiting approvals.
TIMOR GAP’s proposed acquisition of Osaka Gas Australia’s 10% Greater Sunrise interest remains subject to governmental and regulatory approvals and other conditions. No completion date has been disclosed. The transaction is covered in more detail above. - Papua LNG farm-down — tied directly to FID.
The 9.1% farm-down by TotalEnergies to ExxonMobil, Santos and ENEOS Xplora remains conditional on regulatory approvals and Papua LNG reaching FID. The current project timetable targets FID for around the end of November 2026, making that the key near-term trigger for transaction completion. - Osaka Gas / BP — second Browse 5% sale still at the approval / pre-emption stage.
Osaka Gas’ acquisition of a 5% Browse interest from BP remains pending approvals. Woodside has reportedly considered exercising its pre-emption rights, but no formal decision has been announced. For now, the Osaka Gas transaction therefore remains the live proposed ownership change.
Questions and feedback
We have created this article through our own research and any opinions are purely our own. If you have any questions or feedback on the article then please leave a comment below, drop me a message, or email support.