M&A in Southeast Asia - 2026 Q3
(Originally published on October 1, 2026)
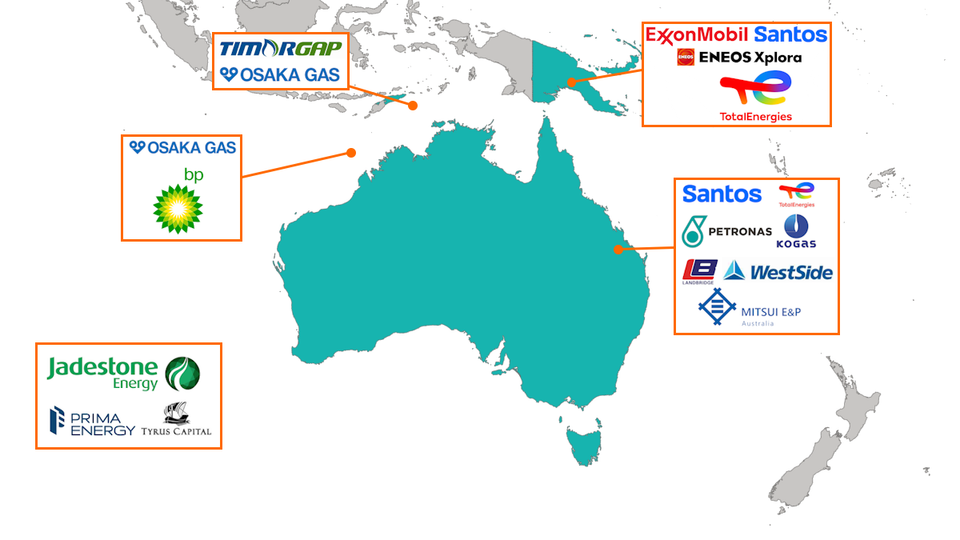
We have recently reallocated Timor-Leste to Southeast Asia rather than Australia. For Q3 2026, however, we have included it within both our Southeast Asia and Australasia regional reviews, with the change reflected retroactively in the regional analysis.
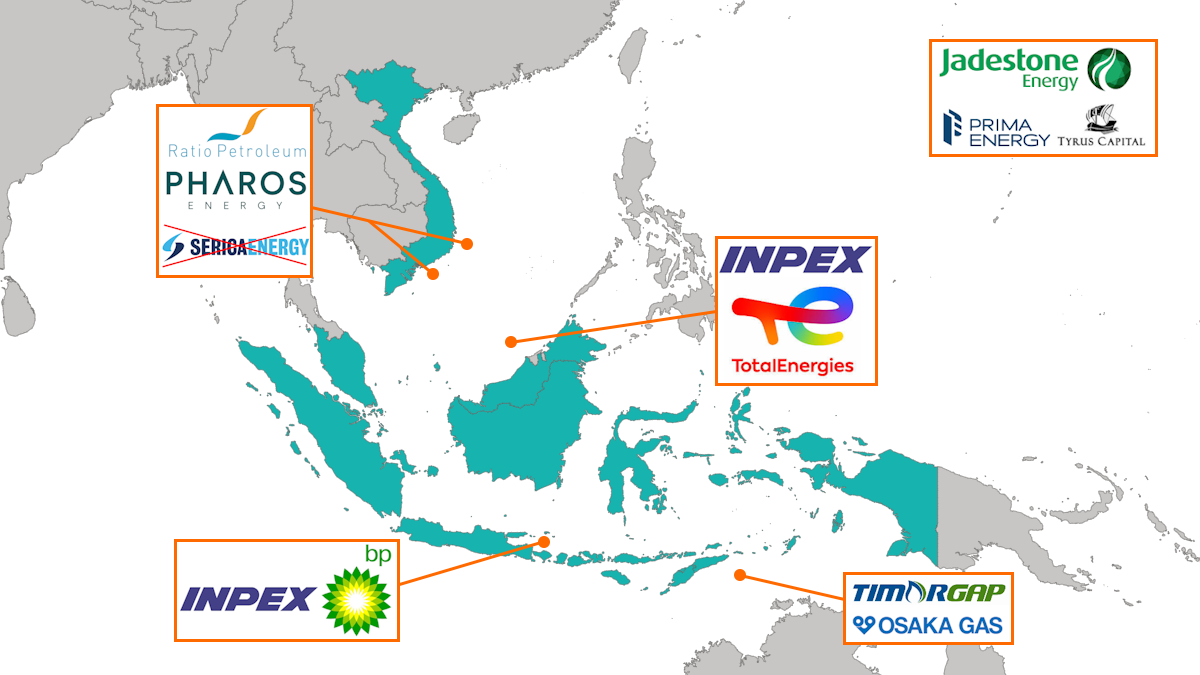
Q3 has seen five deals announced across Southeast Asia, once Timor-Leste is included in the regional scope. The quarter included one Malaysian asset transaction, one Indonesian exploration farm-in, one Timor-Leste project transaction, one regional corporate shareholding transaction involving Jadestone Energy, and one competing corporate proposal involving Pharos Energy’s Vietnam and Egypt portfolio.
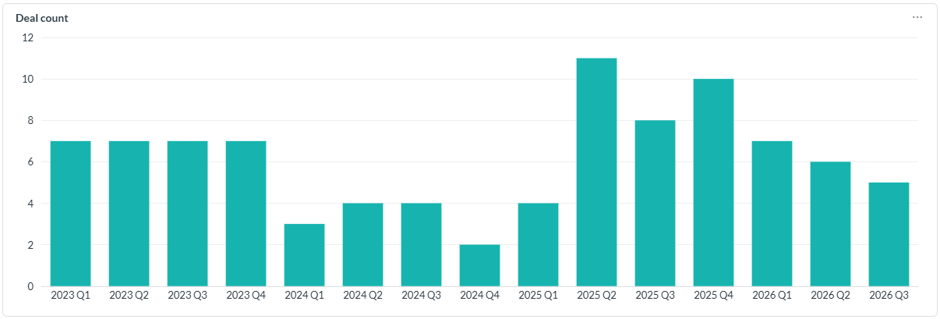
Of the five deals announced during Q3, two had disclosed transaction values: INPEX’s US$350 million acquisition of TotalEnergies’ interest in Block 2E offshore Malaysia, and Serica’s competing proposal for Pharos Energy. However, we have excluded the Serica proposal from our value analysis as it lapsed during the quarter and was superseded by the revised Ratio Petroleum offer.
Instead, we include the revised Ratio / Pharos transaction value, which increased during Q3 and remains the live transaction. This gives a total visible deal value for the quarter of approximately US$544 million. Ratio / Pharos is excluded from the regional chart below because we classify it as a “Global” deal, reflecting Pharos’ assets in both Vietnam and Egypt.
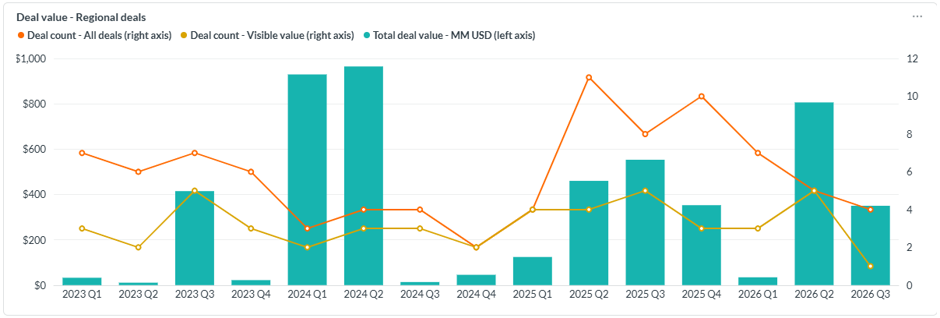
The rolling deal count for 2026 now stands at eighteen Southeast Asia-related deals, with total disclosed deal value of approximately US$1.58 billion from eleven deals with visible value. By comparison, at the end of Q3 2025, the rolling deal count for the year was 23 Southeast Asia-related deals, with total disclosed deal value of approximately US$1.14 billion from thirteen deals with visible value.
New deals announced in Q3
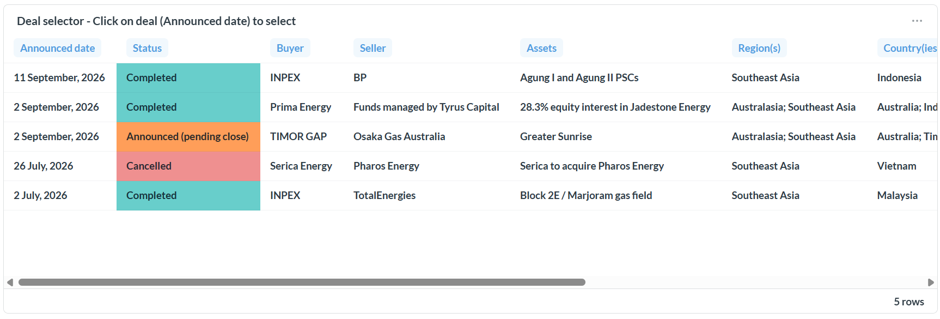
The five deals announced in Q3 were:
- In early-July, INPEX acquired TotalEnergies’ 85% participating interest in Block 2E offshore Malaysia for US$350 million. The interest represents an 8.5% net interest in the Marjoram gas field development, and INPEX also became operator of the block. The transaction was announced and completed on 2 July. We looked at the deal in more detail here.
- In late-July, Serica Energy announced a competing cash acquisition proposal for Pharos Energy, after Pharos had already recommended the earlier Ratio Petroleum offer. The deal would have given Serica exposure to Pharos’ producing and exploration interests in Vietnam, as well as its Egyptian portfolio. However, after Ratio Petroleum increased its offer, Pharos withdrew its recommendation of the Serica proposal, and Serica’s offer subsequently lapsed and was terminated in August. We looked at the deal in more detail here.
- In early-September, Prima Energy acquired a 28.3% equity interest in Jadestone Energy from funds managed by Tyrus Capital. This is a secondary share transaction rather than an asset sale, but it gives Prima Energy strategic exposure to Jadestone’s regional portfolio across Australia, Malaysia, Indonesia and Vietnam. Prima stated that it does not intend to make a full takeover offer. We looked at the deal in more detail here.
- Also in early-September, TIMOR GAP agreed to acquire Osaka Gas Australia’s 10% participating interest in the Greater Sunrise gas and condensate project. If completed, the deal would increase TIMOR GAP’s interest from 56.56% to 66.56%, with Woodside retaining 33.44% and operatorship. The transaction remains subject to governmental and regulatory approvals and customary conditions precedent. We looked at the deal in more detail here.
- In mid-September, INPEX acquired a 50% participating interest in each of the Agung I and Agung II deepwater exploration PSCs in Indonesia from BP. Following the transfer, BP and INPEX each hold 50%, with BP retaining operatorship. No transaction value was disclosed. The deal strengthens the existing BP / INPEX partnership in Indonesia and adds to INPEX’s renewed exploration push in the country. We looked at the deal in more detail here.
The table below summarises the deals announced this quarter:
Deals that were cancelled in Q3
There was one Southeast Asia-related deal cancelled during the quarter.
- In mid-August, Serica Energy’s competing offer for Pharos Energy lapsed after Ratio Petroleum increased its offer and the Pharos board reinstated its recommendation of the Ratio transaction. Serica’s proposal had only been announced in late-July, so the bidding contest was relatively short-lived. The surviving Ratio / Pharos transaction remains pending and is discussed below.
Deals that closed in Q3
Q3 also saw six transaction completions or implementation events across Southeast Asia. Three related to deals announced during the quarter, while three involved transactions announced previously.
- In early-July, INPEX completed its US$350 million acquisition of TotalEnergies’ 85% participating interest in Block 2E offshore Malaysia. The transaction was announced and completed at effectively the same time, with INPEX also becoming operator of the block. We looked at the deal in more detail here.
- In early-September, Prima Energy completed its acquisition of approximately 28.3% of Jadestone Energy from funds managed by Tyrus Capital. The transaction gives Prima strategic exposure to Jadestone’s upstream portfolio across Southeast Asia and Australia. We looked at the deal in more detail here.
- Also in early-September, PT Rukun Raharja / RAJA completed its acquisition of a 5% equity interest in PT Layar Nusantara Gas from Genting LNG. The final consideration was approximately US$43.7 million. This transaction covers the downstream gas-processing and FLNG company associated with the Kasuri development; the related upstream Kasuri PSC farm-down remains pending. We looked at the deal in more detail here.
- In Indonesia, INPEX completed the acquisition of 50% interests in the Agung I and Agung II PSCs from BP following government approval. BP retains operatorship, with the two companies now holding 50% each. We looked at the deal in more detail here.
- In mid-September, Conrad Asia Energy / WNEL completed the farm-down of a 75% non-operated interest in the Duyung PSC to PT Nations Natuna Barat following Indonesian government approval. Completion triggered a further US$4 million payment to WNEL. The separate settlement arrangements between Conrad / WNEL and Empyrean Energy are not yet fully documented. We looked at the deal in more detail here.
- Also in September, Vista Energy completed its acquisition of Lion Energy’s 2.5% indirect interest in the Seram Non-Bula PSC following final Indonesian government approval. The transaction had been awaiting approval for considerably longer than originally expected.
Previously announced deals still pending completion
At the end of Q3, twelve Southeast Asia-related transactions remain pending.
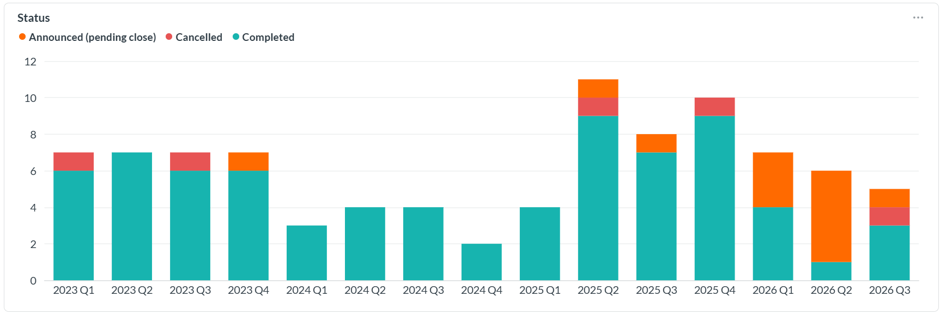
The position varies considerably: some are now close to administrative completion, others have clear completion dates, while a few older transactions have become increasingly uncertain.
- Criterium Energy / Bulu PSC — status increasingly unclear.
The oldest outstanding transaction dates to December 2023, when Criterium Energy signed an LOI relating to a proposed sale of its interest in the Bulu PSC, followed by a formal agreement in May 2024. There has still been no completion announcement. More importantly, Criterium’s latest 2026 materials continue to show the company holding a 42.5% interest in Bulu and actively working on development and monetisation plans. That suggests the previously announced sale has not progressed as originally expected, although I have not seen a formal termination announcement. - PetroVietnam / Zarubezhneft — implementation continues.
The May 2025 cross-border arrangement covers PetroVietnam’s proposed participation in the Kharyaga PSA in Russia and Zarubezhneft’s future participation in Vietnam Blocks 01/17 and 02/17. There was tangible progress during 2026, with the parties exchanging investment documents relating to the two Vietnam PSCs and the Kharyaga participation in June. No firm completion date for the Vietnam interests has been disclosed, although implementation of the broader arrangement continues to move forward. - Valeura / PTTEP — now very close to completion.
Valeura Energy’s farm-in to Blocks G1/65 and G3/65 in Thailand has made substantial progress. The Thai Cabinet approved the transfer in September, under which Valeura will acquire a 40% non-operated interest from PTTEP. Valeura and PTTEP have also taken FID on the first phase of the Bussabong gas development. Valeura said the remaining transfer of interest was expected to be an administrative step in late-September or early-October and that it did not expect to make a further announcement specifically on completion. - Saba Energy / Nido — execution risk has increased.
Saba Energy’s proposed farm-in to Nido’s interests in the Philippines remains uncertain. Under the amended agreement announced in May, Saba was required to raise US$7 million by 31 July 2026. I have not seen confirmation that this condition was satisfied, and the company subsequently received a failure-to-file cease trade order in August after missing its extended financial-reporting deadline. There is currently no revised transaction completion date. - Empyrean / Conrad / Duyung — most of the restructuring is now complete.
The wider Duyung ownership restructuring has largely progressed during Q3, with the 75% Nations farm-down completing in September. Empyrean Energy’s remaining economic entitlement through the WNEL structure is now much narrower in scope but is still subject to completion of final documentation. Empyrean said in September that, once documented, it will be entitled to 8.5% of cash payments to WNEL, including future gas-sale revenues from Mako. - MedcoEnergi / Simenggaris — no visible progress since the SPA.
MedcoEnergi entered into a conditional sale and purchase agreement in February 2026 to divest its interest in the Simenggaris PSC. The buyer has not been publicly identified, and I have not seen a subsequent completion announcement or expected closing date. - Angkor Resources / 358140 Alberta — commercial structure agreed, but final completion remains unclear.
In April, Angkor Resources agreed revised terms with 358140 Alberta that would increase Angkor’s interest in Cambodia Block VIII from 20% to 75%, in return for assuming drilling funding obligations and making a US$2 million payment. The agreement was subject to TSX Venture Exchange approval. Operational work on Block VIII has continued, including EIA work and drilling preparation, but I have not seen a clear public announcement confirming final completion of the ownership transaction. - RATU / Genting — upstream Kasuri farm-down still expected by February 2027.
The related downstream transaction involving PT Layar Nusantara Gas completed during Q3, removing an important condition for the upstream leg. PT Raharja Energi Cepu / RATU’s acquisition of a 5% participating interest in the Kasuri PSC from Genting remains pending, with the original timetable pointing to completion no later than February 2027. - EnQuest / PETRONAS Carigali — effectively de-risked, with completion scheduled for year-end.
EnQuest’s acquisition of interests in four Malaysian PSCs has progressed substantially since its June announcement. Shareholders approved the transaction, PETRONAS issued its farm-out approval, and existing partners waived the relevant Package 2 pre-emption rights. EnQuest announced in August that all conditions precedent had been satisfied and continues to expect completion on 31 December 2026, with an economic effective date of 1 January 2027. - Sinopetro / Interra — still awaiting shareholder approval and other conditions.
Interra Resources agreed in June to sell its Myanmar interests in the Chauk and Yenangyaung fields to Sinopetro Holdings. Interra continues to describe the disposal as conditional and says shareholder approval will be sought at an extraordinary general meeting. No completion date has yet been announced. - Ratio Petroleum / Pharos Energy — shareholder-approved, targeting H1 2027.
Following the lapse of the competing Serica proposal, the Ratio Petroleum transaction is now the surviving offer for Pharos Energy. Pharos shareholders approved the scheme in late-August. Completion remains subject to regulatory approvals, including in Vietnam and Egypt, and court sanction. Pharos continues to expect the transaction to become effective during the first half of 2027. - TIMOR GAP / Osaka Gas — recently announced and awaiting approvals.
TIMOR GAP agreed in early-September to acquire Osaka Gas Australia’s 10% interest in Greater Sunrise. The transaction remains subject to the required approvals and conditions, with no completion date disclosed. As one of the new Q3 deals, it is covered in more detail above.
Questions and feedback
We have created this article through our own research and any opinions are purely our own. If you have any questions or feedback on the article then please leave a comment below, drop me a message, or email support.